When you’re in the middle of a project, it’s sometimes hard to imagine the final result. But, that stash of cash in your 401(k) will someday be your income, and you’ll be taking money out of it rather than putting money in it.
The strategies for investing while you’re taking withdrawals are significantly different from the strategies for investing while you’re still saving. Funds that guard against big losses in a bear market, for instance, might be better than those that post big gains in a bull market.
To illustrate how dramatically withdrawals can change your investment strategies, take a look at how the 15 largest stock funds of 1996 would have fared after 10 years of withdrawals. 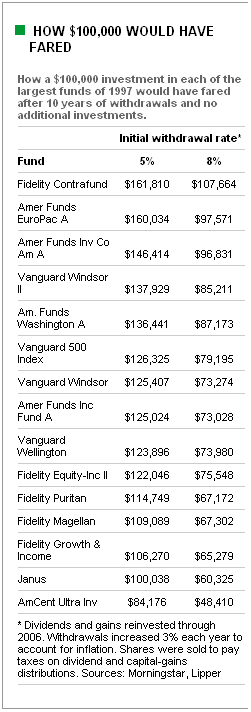
This 10 year period is telling because the decade encompassed pretty much every type of investment phase imaginable. Stocks enjoyed an astonishing bull market from 1997 through 2000, endured a bone-jarring bear market from 2000 through 2002 and finally skated through a relatively mild bull market for the rest of the period.
Naturally, funds that produced the highest total returns in the past 10 years left you with the most money at the end of the period. Fidelity Contrafund gained about 180% for the 10 years that ended in 2006. Even after withdrawing $106,259 — an initial 8% withdrawal rate — you’d still have $107,664 left in your account after 10 years. But, avoiding big losses was even more important than scoring big gains.
American Century Ultra jumped 42% in 1999, compared with 25% for Fidelity Contrafund. By the end of 1999, your Ultra balance would have been $166,741, vs. $152,223 for Contrafund, assuming you began with an 8% withdrawal rate.
Bear markets, though, hurt you much more when you’re taking money out of your account. Ultra lost 19.9% in 2000, 14.6% in 2001 and 23.2% in 2002. By the end of 2002, your Ultra account would have fallen to $66,520, including withdrawals.
By contrast, Contrafund’s worst calendar-year loss from 2000 through 2002 was a 12.6% tumble in 2001. By the end of 2002, your Contrafund account would have stood at $86,372.
A 1998 study by three professors at Trinity University in Texas looked at success rates in retirement, using different withdrawal rates. Success, to the authors, meant having money left after 30 years. They reviewed stock returns from 1926 through 1995 and adjusted withdrawals for inflation each year. If you started with a 5% withdrawal rate in an all-stock portfolio, your success rate was 85%. If you started with an 8% withdrawal rate, your success rate plunged to 41%.
The Trinity study found that an all-bond portfolio had just a 17% success rate after 30 years — and that’s if you started with a 5% withdrawal rate. A mix of 50% stocks and 50% bonds raised the success rate to 76%.
The top funds of any given 10-year period will rarely be the best funds over the next 10 years. But, if you start taking small withdrawals and try to limit your losses by choosing an appropriate asset allocation, your money could last longer than you imagine.